How Small Tax Firms Batch and Prioritize High-Volume IRS Notice Responses Using AI Drafting Queues
AI queues route IRS notices by type and deadline to speed firm responses.
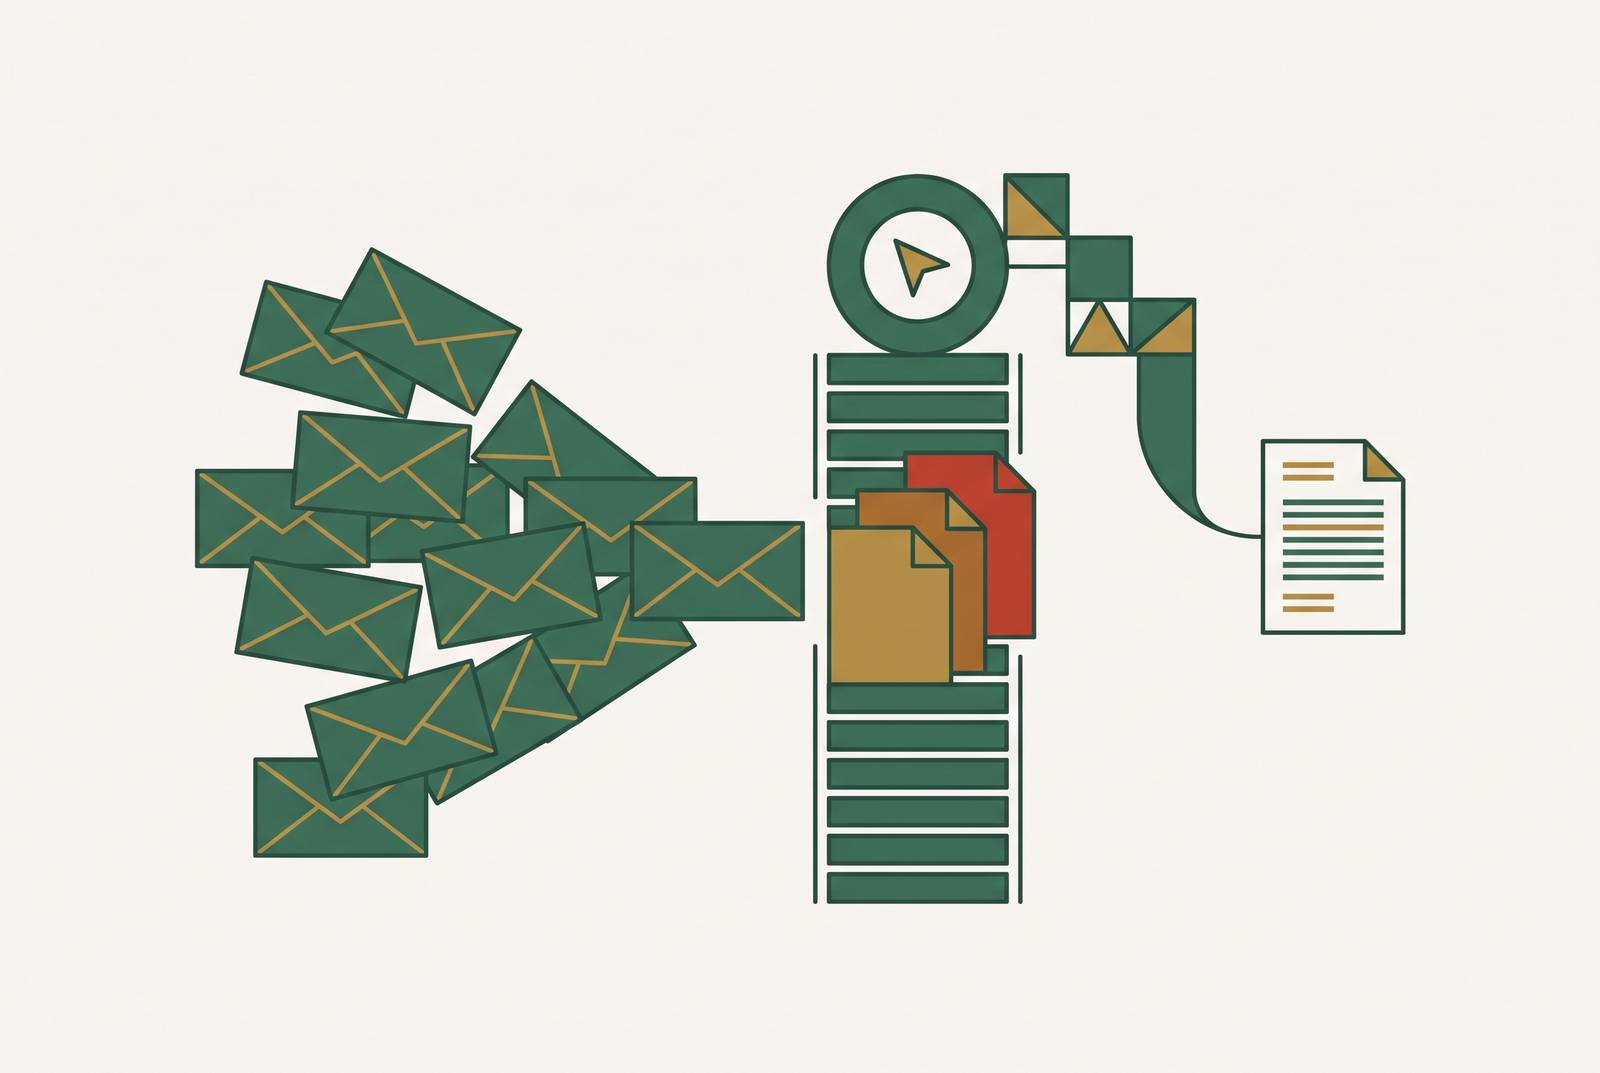
Small tax firms can respond to IRS notices faster with AI drafting queues that group cases by notice type and deadline and require a practitioner to review each response and record that review before it is sent. Purpose-built tax AI can combine research and response drafting, but the operating discipline is decisive. A defensible queue assigns responsibility at every handoff, from extracting the notice’s facts to tracking the IRS’s response.
Why small tax firms are absorbing more IRS notices than they can handle manually
Small tax firms face two converging pressures. The IRS has expanded automated enforcement capacity while shrinking its human workforce, increasing the burden of handling notices while making resolution harder to obtain. More third-party reporting adds another recurring source of discrepancies. Form 1099-DA, effective for the 2025 tax year, gives the IRS a direct reporting trail for digital asset transactions. A mismatch between broker-reported proceeds and a taxpayer’s return can trigger a CP2000.
IRS guidance FS-2025-06 explains the asymmetry behind that mismatch. Brokers report gross proceeds and may voluntarily report cost basis, but basis reporting is not required for 2025 transactions. Taxpayers still have to calculate their own basis. That division creates a predictable, recurring reconciliation problem. GAO-26-107522 found that a majority of the IRS’s 126 AI use cases were still listed as “in development” as of June 2025, indicating further automation ahead. Firms therefore need a way to handle notices as they keep coming in as well as clear the temporary backlog.
What an AI drafting queue actually is and how it differs from ad-hoc AI use
An AI drafting queue is a repeatable, role-assigned workflow that moves each notice through intake, response drafting, and practitioner sign-off. Its three functional layers are document intelligence, which reads and classifies the notice, language generation, which produces a structured response, and practitioner review, which tests the output before release. Each step is documented, governed by a notice-specific template, and assigned to a named role. Unlike pasting a notice into an assistant, this process does not depend on whoever happens to be at the keyboard.
The choice of drafting system affects whether that process is defensible. General-purpose assistants such as ChatGPT, Claude, and Gemini can hallucinate citations on tax-specific queries, while purpose-built tax platforms retrieve from curated primary-authority databases. Their citations give the reviewer sources to check. Verification remains essential in either case. The Tax Court case Clinco illustrates the stakes, with an attorney citing four cases in support of an argument and the court describing three as likely hallucinations generated by a large language model. A fabricated citation offers no defense for the position it supposedly supports.
Intake: scanning, separating, and capturing the facts the queue needs
Notices arrive as single PDFs, batches, and multi-notice PDFs containing several cases in one file. The intake system for the queue needs to scan, separate, and parse these formats without staff having to sort them by hand. Each notice needs its own structured record containing the raw document and extracted fields, including entity, notice type, tax year, proposed change, and deadline. Those fields are the inputs for routing and drafting.
The upload decision comes before automated processing. IRC §7216 can apply when sending client data to an outside AI vendor constitutes disclosure of taxpayer return information. That decision belongs here because a later drafting or review control cannot substitute for an authorized disclosure. Once data handling is settled, the structured record gives the rest of the queue a common factual starting point. Without it, staff must repeatedly reopen the notice to determine what happens next.
Triage logic: batching notices by type and sorting by deadline
Triage replaces arrival order with two organizing rules. Notice type determines the response workflow, while deadline determines priority within the batch and can override normal batch order. AI detects the notice type and deadline, then routes the case to the appropriate checklist. A CP2000, which proposes changes through the Automated Underreporter system, belongs in a substantive factual-response batch when the proposed change is disputed. A CP14, an initial balance-due notice, typically routes to payment or an installment agreement instead.
A CP504 requires a different priority decision. As an intent-to-levy notice with a hard deadline, it moves to the top of the queue regardless of when it arrived. CP2000 deadlines also require close attention because ignoring the notice can trigger a statutory notice of deficiency, leaving a narrow window to petition Tax Court before assessment and collection. The practical batch checklist identifies facts to verify, client documents to request, the deadline, and the role responsible for the first draft.
Within the CP2000 workload, 1099-DA-driven discrepancies are strong candidates for a dedicated batch. The recurring distinction between broker-reported gross proceeds and client-reported basis supports a reusable template and a focused checklist. Drake Tax’s batch extensions feature already applies it to generating and e-filing Form 4868 for many clients at once. Notice queues use the same approach for responses, with deadlines and review for each case.
Prompt templates by notice type: building the drafting engine that runs the queue
Once triage establishes the response path, the template turns structured facts into a draft. Firms building this engine should maintain a separate prompt template for each notice type, with version control and a name identifying the type, version, and date. CP2000_Response_v2.1_2025-07-15 is one such convention. Templates should be reviewed quarterly or whenever IRS procedures change. Versioning makes the drafting instruction identifiable rather than leaving staff to reconstruct which prompt produced a response.
The template receives anonymized facts extracted at intake, including notice type, tax year, proposed adjustment, and the client’s basis or supporting documentation. It returns a response organized around a salutation, statement of facts, legal basis, requested relief, and attachments list. The structure is repeatable, but the facts remain individual. For a CP2000, producing language around the practitioner’s facts saves the time needed to compose the response from scratch. The practitioner still has to verify the response, do the supporting computations, and sign it.
TaxGPT lets users work on CP2000, CP14, CP503, and CP504 responses in the same place where they do citation-backed research. Blue J lets users upload notices and supporting documents as Project Files, grounding engagement threads in the same materials without repeated uploads and turning research into a draft within that workspace. Its plan for an individual practitioner costs $1,498/user/year and has a 7-day free trial. The practitioner must be able to open the underlying IRC section, Treasury Regulation, or IRS guidance and check whether it supports the draft.
Practitioner review gates: what Circular 230 requires at every handoff
IRS OPR Alert 2026-19, issued June 24, 2026, clarifies that AI does not change a practitioner’s Circular 230 obligations. Every AI-generated document requires thorough review before delivery to a client or submission to the IRS. The applicable provisions include §10.22 on due diligence, §10.35 on competence, and §10.37 on written advice. Review therefore covers facts, the existence and meaning of cited authorities, and the accuracy of calculations. The obligation extends to AI-drafted client memos as well as notice responses.
In the queue, that obligation becomes a named checkpoint. The practitioner signs off on the factual statement, every citation, the supporting computation or documentation, and the relief requested, with the sign-off logged in the file. An informal read-through leaves no equivalent record of what was evaluated. Documented review also makes delegation workable because staff know which questions the senior practitioner must resolve before release. The gate enables speed by giving the drafting process a defined boundary.
The consequences of bypassing that boundary are professional. Financial penalties, public censure, mandatory ethics courses, and disciplinary referrals to state licensing authorities are possible sanctions. Clinco illustrates why fabricated AI citations are treated as a professional conduct failure. Even if its drafts read well, a queue falls short of compliance when it lacks a recorded review step and file trail. Neither plausible language nor a citation-backed interface establishes that a particular response is correct.
Staffing and role assignment inside the queue
A two-role model is proportionate to most small firms. An AI champion, typically a senior CPA, owns template creation, updates, and the final review gate. A queue operator, who may be a junior staff member or paraprofessional, handles intake, triage routing, and initial draft generation with the approved template. The division separates mechanical production from substantive responsibility. It does not transfer the senior practitioner’s judgment to either the operator or the software.
The template makes that delegation more consistent. The operator runs a documented process rather than deciding independently which tax position the firm should take, and the senior reviewer evaluates the resulting response. A sole practitioner can retain the same distinction without adding staff. In that setting, the same person drafts with the template and then reviews the work and records the review as a separate step.
Tracking and closing notices: the file trail the queue must maintain from intake to resolution
Sending a response does not close the notice. The queue continues tracking the case through IRS acknowledgment and final resolution, particularly as reduced IRS human staffing has lengthened response times. Closing the file at dispatch removes the firm’s early warning of a follow-on notice or statutory notice of deficiency. The tracking record therefore retains the date received, date sent, POA status, any follow-on notice, and the date the case closes. Those entries help show that the firm has met its duty of due diligence.
Batch processing also supplies a review rhythm. At the close of each batch cycle, the AI champion reviews every open notice in that batch, escalates approaching statutory deadlines, and confirms that client communication has been sent. The original intake fields, including entity, notice type, and deadline, become the basis for this status view. A separate case management system is not necessary if the queue’s records remain searchable and date-stamped.
Building the queue incrementally: a starting point for firms that have not automated notice response before
A firm starting from manual notice handling does not need to automate every notice type at once. The firm should start with its highest-volume, most templatable category, typically CP2000. The emerging 1099-DA-driven variant is another strong candidate because its mismatch pattern is predictable. One prompt template, tested against recent actual notices, and one documented review checklist establish the initial workflow. The estimated eight-to-twelve-hour investment builds a reusable foundation that can be refined with each new case.
The first batch then runs through the complete cycle of intake, triage, drafting, review, sending, and tracking. Its results guide changes to the template and checklist before the firm adds another notice type. Before scaling, the firm should also confirm that its vendor relationship meets confidentiality requirements and that its IRC §7216 protocol remains part of intake.
Purpose-built tools can reduce the coordination cost of this initial build when they integrate intake, research, citation-backed drafting, and document analysis. That is a structural advantage, with every handoff still required. A combined workspace is useful to the extent that it keeps the operator and reviewer working from the same engagement materials. Expansion can follow after the first complete batch exposes what needs adjustment. This week, select one frequently received notice type and assemble recent examples to develop its first prompt template and review checklist.