Gain Recognition Agreements in Cross-Border Asset Transfers Under IRC 367
Deferred gain requires a five-year agreement with the IRS.
Omar Delacroix
Section
7 stories in Tax Valuation Concepts.
Deferred gain requires a five-year agreement with the IRS.
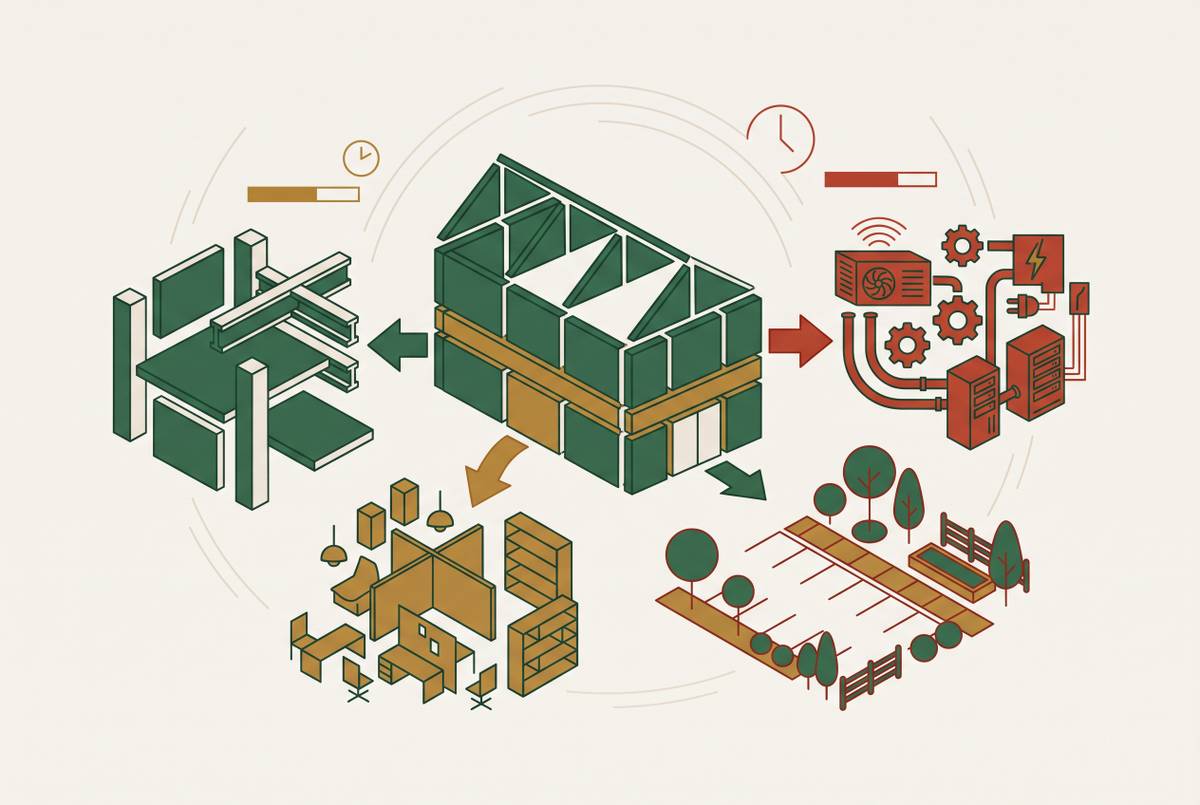
Engineers break down building costs into faster depreciation buckets.
Accurate valuations on conversion day determine your tax exposure for five years without revisement.
Two valuation methods produce vastly different numbers for the same intangible asset.
How pass-through entities face steeper illiquidity discounts than C-corp stakes.
Getting the strike price right protects employees from unexpected tax penalties.
Goodwill valuation hinges on method selection and rate assumptions.