When to Hire vs When to Automate in a Solo Tax Practice
Automate repetitive tasks while keeping judgment work for yourself to scale without hiring.
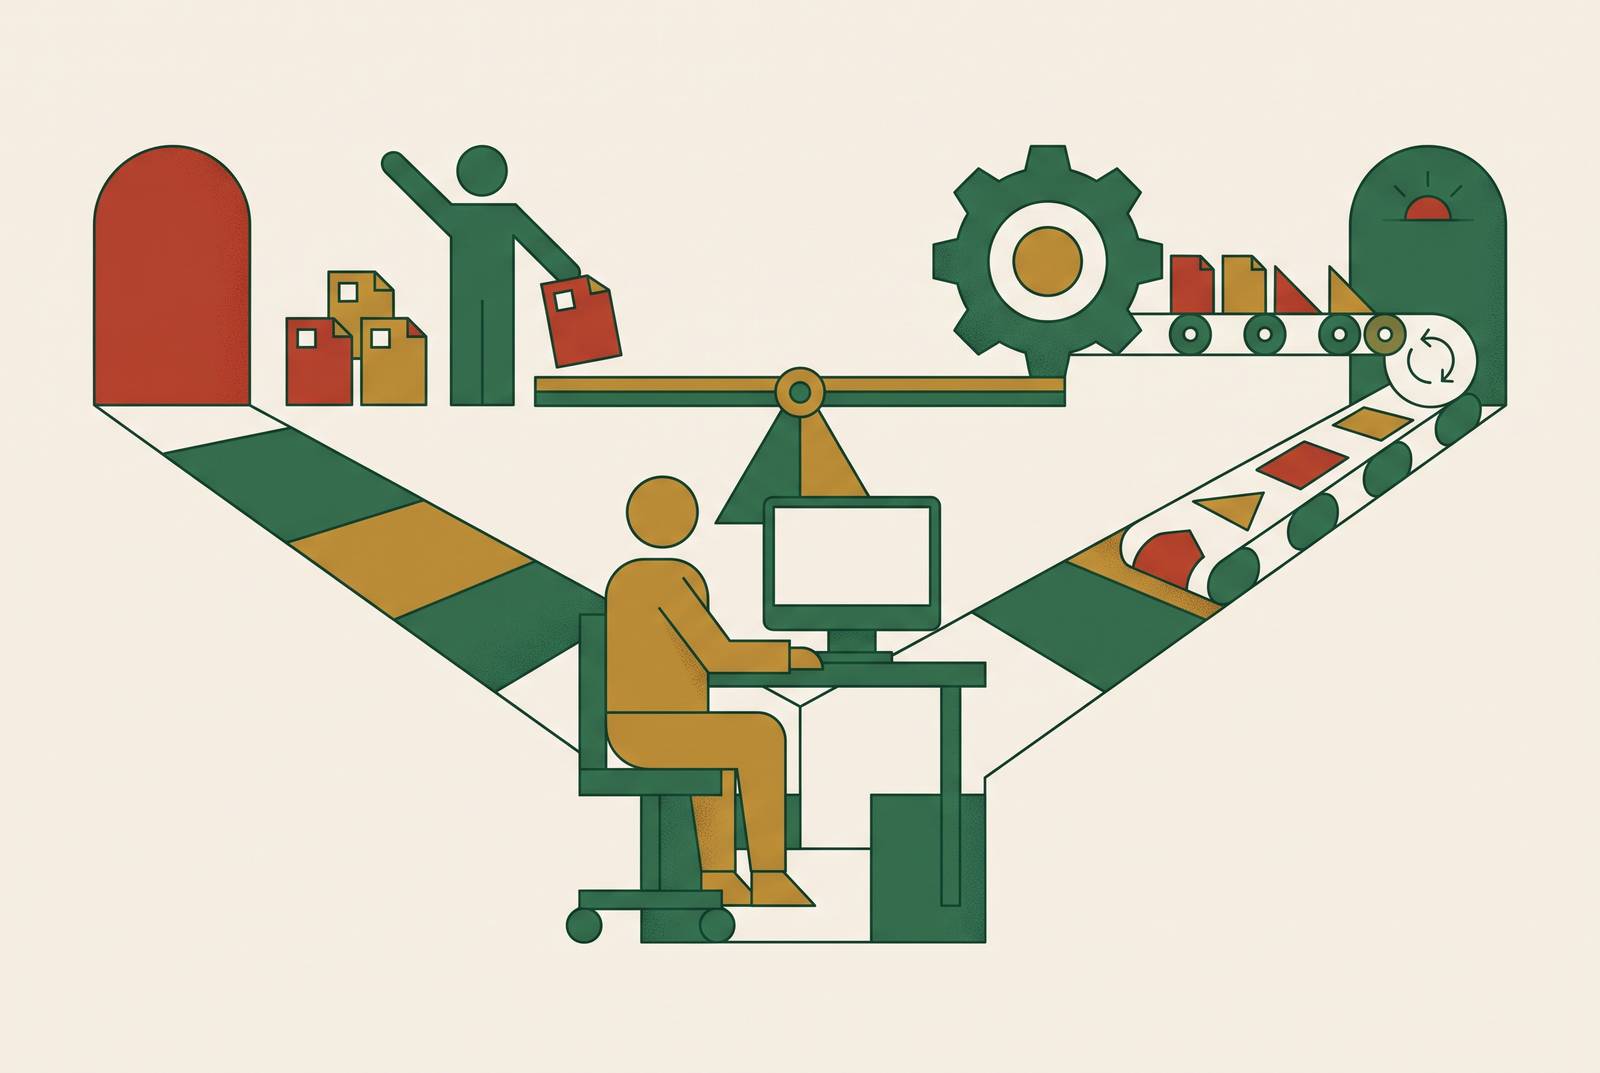
A solo tax practice can scale without hiring by automating rules-based intake, administration, and preparation while keeping professional judgment, representation, and client trust with a human. The hire-vs-automate decision begins with the nature of the work. Hiring makes sense when the practitioner has more judgment-heavy work than one person can handle, while automation can take on routine tasks that fill the day.
Why the hire-vs-automate question keeps coming up wrong for solo practitioners
A strained schedule makes additional headcount look like the obvious answer. But a full calendar does not identify the constraint. Document chasing, routine preparation, and IRS representation all consume time, yet each calls for a different response. Comparing the cost of a preparer with the cost of software before separating those tasks treats unlike work as interchangeable. The financial comparison belongs after the practitioner has established what the additional capacity must do.
Administrative drag is a workflow problem before it is a staffing problem. A person can chase documents, send reminders, and route intake, but hiring someone costs more and leaves the same snags in the workflow. Where the sequence follows known rules, automation can address the repetitive work itself. By contrast, a practice struggling with multi-entity structures or client advisory has a shortage of professional attention. Software cannot resolve that shortage simply by processing information faster.
Diagnosing the workflow therefore requires distinguishing work that needs the practitioner’s judgment from work that merely requires the practitioner’s time. Both kinds of work often come up for the same client. Treating an entire return as either automatable or human-only obscures the distinction between extracting figures and deciding whether a tax position is appropriate. That framing error produces two predictable mistakes, namely hiring a preparer for work software could handle and buying software for work that requires a qualified human. A task-level decision avoids both.
Why finding and affording qualified help has become structurally harder
With too few accountants to go around, those mistakes are harder for a practice to bear. Accounting program enrollment fell for several years, although enrollment rebounded in 2024–2025. Experienced practitioners retire or move into industry roles faster than new entrants replace them. The rebound does not immediately replenish experienced tax talent. Solo practices therefore face a structural constraint rather than a temporary hiring cycle they can simply wait out.
National firms can offer higher pay and clearer paths to move up, so solo firms have a harder time hiring when candidates choose jobs mainly for the salary. Seasonal help has also become harder to find. Thomson Reuters’ tax industry panel included a firm that could no longer attract seasonal interns and redirected investment toward software and automation. In that case, the traditional busy-season pressure valve was no longer available.
A W-2 staff preparer brings employer payroll taxes, software costs, workspace overhead, and a period of supervision. During the first year, that supervision can reduce the owner’s own productive capacity and take-home pay before the hire becomes net positive. Agency placement fees can add to what the practice pays upfront. The relevant comparison is not simply a wage against a software subscription, but the capacity each option actually adds after its demands on the practitioner.
Scarcity raises the bar for assigning scarce professional labor to repetitive work. A practitioner who needs another person’s judgment still needs to recruit, even when that process is difficult. A practitioner who needs fewer reminders to send has a different problem. Automation must be part of the capacity strategy because qualified help is both harder to secure and too valuable to use primarily for administrative repetition.
The task-type boundary that actually separates what automation can and cannot do
The useful boundary separates known rules applied to structured inputs from decisions made under ambiguity. Document intake and OCR, expense categorization, form data entry, basic return calculations, reminders, e-signature routing, and extension triggers fall largely on the rules-based side. Their repetition makes them suitable for automation. Choosing an entity structure, interpreting uncertain multi-state guidance, or researching an unusual position requires a different kind of work. Those decisions depend on facts, risks, and context that may not appear in the documents.
Consider a client who sold a rental property held for nine years, refinanced twice, and used part of the home as an office. Software can handle depreciation recapture mechanics. It cannot establish from those mechanics alone whether office use was exclusive and regular, how refinance proceeds were used, or whether the property was rented below market to a relative. Those questions require conversation and professional recognition of what looks slightly wrong in the file.
The calculation therefore follows the fact-finding. A technically sound calculation can still rest on an incomplete account of the client’s circumstances. The same distinction applies when deciding whether a cost segregation study is warranted or whether an unusual tax position is supportable. Producing an answer is not the same as establishing its basis. Automation can speed up the calculations while leaving a person responsible for deciding whether they apply.
Liability provides the clearest boundary of all. A model cannot hold a preparer tax identification number, represent a taxpayer in an examination, or be sanctioned as a practitioner. The signing practitioner adopts the AI-produced output and owns it. As automation compresses intake, data entry, and calculation, time spent mainly on those tasks becomes more exposed to displacement. People still have to find the facts, interpret them, and take responsibility, so preparation speed alone cannot show how much work a professional can handle.
What should a solo tax preparer automate first to get through busy season without staff?
For a solo practitioner applying this framework, administrative drag is the first automation target. Document chasing, intake routing, engagement letters, e-signature requests, status updates, and estimated payment reminders are repeatable sequences that can be built once and reused each season. They consume time without requiring professional judgment. In a practice handling several hundred returns, administrative chasing alone absorbs a meaningful number of hours. Recovering even a fraction of that time creates room for billable advisory work without adding another person.
The first pass should remove friction before tackling complexity. Its purpose is not to replace a preparer, but to stop the practitioner from doing work that requires no tax expertise. For administrative work, the relevant capabilities are intake, workflow routing, reminders, and signature coordination. For preparation support, the relevant capabilities shift to document classification, reconciliation, and first-draft preparation, with human review remaining part of the work.
Those workflow categories are more useful than a single claim about the “best AI software” for enrolled agents. A tool that accelerates drafting does not necessarily address a bottleneck in document collection. Conversely, an efficient intake process does not resolve a file with ambiguous facts. Purpose-built tax automation is built for intake, routing, and compliance checks that leave the preparer accountable, while generic productivity software has to be adapted to that work after the fact.
Preparation support also demands a stricter review discipline. Models can reference outdated statutory authority, invent code sections or revenue rulings, and give overconfident answers on gray-area positions. Faster output is not finished work. AI-assisted classification, reconciliation, and drafts still require a qualified human to review and adopt them. Rapid adoption without a review governance process can increase liability exposure rather than reduce it, so the capacity calculation must include the professional attention needed to assess the output.
When the work actually calls for hiring a human instead
Hiring is appropriate when judgment-heavy, relationship-dependent, or representation work exceeds what one licensed practitioner can manage. Schedule K-1s from partnerships or S corporations, rental real estate with depreciation recapture, and multi-state filings with unclear nexus positions all call for a professional’s attention. Equity compensation, digital assets with unreliable cost basis, and FBAR exposure belong in that category as well. Their significance lies in the questions they raise.
Representation establishes a firm limit on substitution. IRS Circular 230 gives CPAs, enrolled agents, and attorneys unlimited representation rights, which software cannot hold no matter how much it can do. A practice with more examination or representation work than its owner can handle needs credentialed human capacity. Automating the surrounding administration can make that work easier to manage. It cannot supply the representative.
Invoice Home’s second annual U.S. Tax Filing Report found that, in 2026, the share of taxpayers who would consider trusting AI over a tax professional declined compared with 2025. The decline extended across every generation. That finding supports a human-in-the-loop model rather than an assumption that clients want the professional removed.
The hiring profile has changed accordingly. In 2026, a pure data-entry preparer rarely justifies headcount as well as someone who can supervise automated output, recognize an error, and hold an advisory conversation. Hiring for oversight and advice addresses the work automation leaves behind.
Implementation time remains a legitimate objection for a stretched solo practice. Reviewing software and changing workflows take time and resources that a practice may not have during busy season. For a practitioner in that position, evaluating changes in fall or extension season avoids peak-season pressure. The same panel said it planned technology changes before the rush. Timing the transition makes automation a capacity decision rather than another urgent project competing with client work.
How the framework changes the growth question itself
The relevant limit becomes how much judgment-heavy, high-value work the practitioner can accept, rather than how many returns can pass through preparation. Recovered time has a different destination. Filling every freed hour with more routine returns would preserve a practice centered on the work automation is compressing. Using that time for advice instead directs professional attention toward decisions that require it.
Preparation economics reinforce that choice. As automation reduces preparation time, billing by the return keeps the practice tied to the economics of routine output and leaves the value of the practitioner’s judgment out of its pricing. Pricing advisory work by outcomes offers a way to protect margin.
Client demand points in the same direction. Thomson Reuters’ 2025 State of Tax Professionals Report found that the majority of surveyed tax firms said their clients strongly desired more tax and business advice beyond return preparation. A solo practitioner does not have to treat automation as a reason to pursue volume for its own sake. The opportunity is to devote more attention to the advice clients are already requesting.
Purpose-built automation can reduce backend administrative work without transferring accountability for any return that leaves the practice. The owner can then hire for the judgment, representation, and client relationships that have become too much to handle alone. A practice can grow without employees where automation releases enough time for that work, but it cannot automate away its professional obligations. The aim is better client outcomes through more available expertise.
Sources
- How tax professionals can harness the power of AI while maintaining professional judgment
- AI loses ground to pros as taxpayers rethink who should do their taxes
- Q&A panel: Expert takes on tax industry trends Q&A panel: Expert takes on tax industry trends
- Intergenerational Solutions to Address the Crisis of the Leaking Accounting Pipeline - The CPA Journal
- ICYMI
- Faster AI, Uneven Frontier: Rapid Crossings, a Jagged Frontier, and the Repositioning of Human Judgment