How Tax Firms Should Think About Project Management
Treating tax work as production, not ad-hoc consulting, fixes management failures.
Tax firms do not struggle because the technical work is hard. They struggle because the way most firms manage that work has nothing to do with how the work actually behaves. A preparer can know the code cold and still watch a return slip past its deadline, an engagement balloon past its price, or a senior associate quit mid-March, and none of that happens because the firm lacks expertise.
The dominant operating model at most firms is informal almost by default. Workflow remains the single biggest challenge accounting firms report, and the specific complaint that now tops the list is not manual administrative drag but something more basic: getting documents from clients on time. That is a telling detail. It means the breakdown often starts before the technical work even begins, at the handoff between client and firm, which is exactly the kind of failure a management system is supposed to catch and an ad-hoc one cannot.
Tax work is a recurring production operation with hard external deadlines
Tax work has a structure, and that structure looks much more like a factory floor than a law office. It runs in recurring cycles. Bookkeeping closes every month, payroll runs every month, quarterly estimates fall on fixed statutory dates, and annual returns are due April 15 with extension windows that simply move the deadline, not remove it. None of those dates are up for discussion. A firm can negotiate its fee, its staffing, even its client list, but it cannot negotiate the calendar.
Accounting project management literature treats this as a defining feature rather than an inconvenience: the work is naturally project-driven, with each engagement carrying known inputs, a fixed sequence of steps, dependencies between staff, a review stage, and a hard delivery date. What matters in that setting is whether the pipeline is moving returns through at the rate the season demands.
That distinction separates tax work from a typical consulting engagement, where the scope, the client, and the approach change every time. Tax work repeats. The same engagement type comes back next quarter and next year, carrying the same steps and the same dependencies, and that repetition means every inefficiency in the system compounds instead of staying contained to one bad week. It also means every fix compounds.
That reframing has consequences for how a firm should measure itself. A production operation is judged on throughput, on cycle time, on how fully staff capacity is being used, not on whether each engagement subjectively feels under control to whoever is running it. Once a firm accepts that its tax practice is a production system with externally imposed deadlines, the tools, the metrics, and the daily management rhythm it needs start to look very different from what most firms currently use.
Talent constraints and a more demanding regulatory environment widen the mismatch every year
Two forces are tightening on tax firms at once: there are fewer people available to do the work, and each engagement now carries more compliance complexity than it did a year earlier. Neither trend is reversing on its own, and together they make the management layer more important than it has ever been, not less.
The talent pipeline has been shrinking for years. The number of candidates sitting for the CPA exam has dropped sharply over the past decade, a large share of currently active CPAs are already at or past retirement eligibility, and firms are losing candidates to better-paying sectors before those candidates ever reach public accounting. Robert Half data cited by Befree shows that heading into 2026, only a small share of finance and accounting leaders believe they have the staff needed for their highest-priority work. Most firms are walking into peak season already short-handed before the first return comes in.
The regulatory environment adds to the staffing shortage instead of easing it. The IRS itself is entering fiscal year 2026 with a significantly reduced workforce and budget, following a drop of roughly a quarter of its employees between January and May 2025. Every one of those changes generates taxpayer confusion and processing errors downstream, and that confusion routes straight into tax firms as a higher volume of client questions and corrections.
What poor project management costs a tax firm
The clearest illustration of the cost is scope creep, and it plays out the same way at firm after firm. The firm just absorbs it.
That absorption is visible in aggregate numbers across a firm's book of clients. Rightworks' 2025 Post-Tax Season Survey found that a share of firms scaled back their tax client base in the prior year simply to match the workforce they had on hand.
Staffing absorbs the rest of the damage.
There's a clear upside on the other side of this ledger. Rightworks' 2025 Accounting Firm Technology Survey found that firms furthest along in technology adoption generate 23% more revenue per employee than firms still early in that journey. The gap between a firm bleeding margin to scope creep and turnover and a firm capturing that 23% premium is a difference in how the work is managed.
Why standard project management frameworks don't transfer cleanly to tax work
The obvious response to all of this is to borrow a project management framework from software or another industry and apply it to tax work. That instinct is reasonable, but most of those frameworks were built around an assumption that does not hold in tax practice: that timelines and scope can flex when circumstances change.
Agile and Scrum, as practiced in software development, assume a team can reprioritize its sprint goals mid-cycle if something more urgent comes up. A tax deadline offers no such flexibility. A tax return doesn't have that option. It either satisfies every filing requirement or it doesn't, and there is no partial, "good enough for now" version of a filed return.
None of that means these frameworks are useless, only that they need translation before they fit. An adapted version of Agile does hold up well in a tax practice: short weekly stand-up meetings to surface blockers before they become deadline problems, capacity checks before work gets assigned rather than after someone's already drowning, and a visual board showing exactly where every return sits in the pipeline. The goal is a throughput target tied to a real deadline.
Adopting a tool without redesigning the process around it is the bigger risk. Tools matter, but they are not the binding constraint. The process standard and the management discipline to enforce it are.
The three management changes that match the production reality of tax work
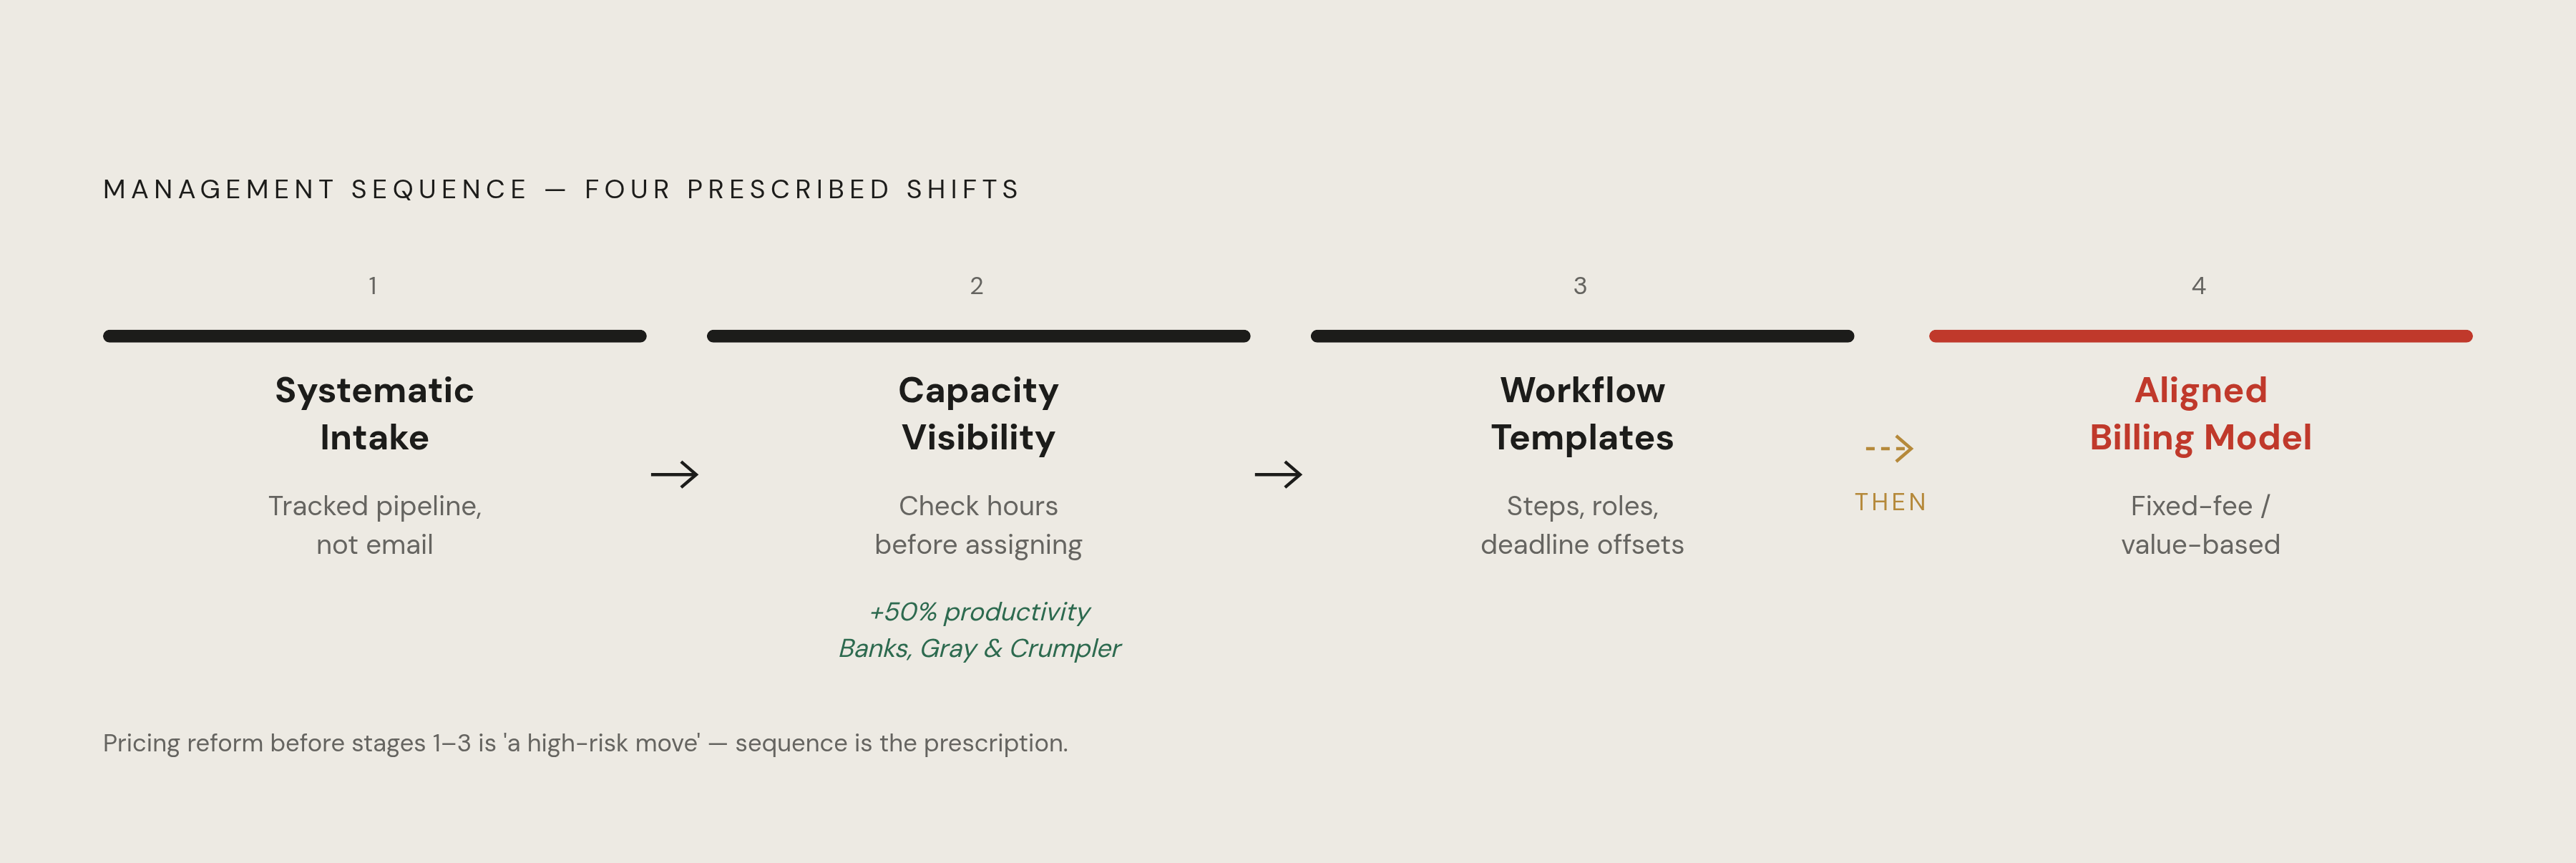
Three specific shifts bring a firm's management layer in line with the production reality of the work: systematic intake, capacity visibility before work gets assigned, and recurring workflow templates that capture what the firm already knows how to do.
Intake comes first because it's the input side of the pipeline, and a pipeline with no reliable input schedule cannot run predictably no matter how well-organized the rest of it is. Getting documents from clients is now the largest single workflow pain point reported by accounting firms, which is a sign that intake isn't a client-relations issue so much as a production-input issue. Firms that treat intake as a structured, trackable handoff, rather than a loose back-and-forth over email, eliminate the single most common cause of pipeline stalls before they ever reach the prep stage.
Capacity visibility comes next. That visibility needs to exist before work enters the queue, not after a staff member is already buried in it. Banks, Gray & Crumpler, PLLC put this into practice by adopting a practice management platform built around capacity visibility, and reported a 50% productivity improvement along with growth in average revenue per employee.
Recurring workflow templates close the loop. Because tax work repeats on a known cycle, every engagement type, whether an individual return, a business return, an R&D credit study, or a quarterly estimate, can be built once as a template with its steps, its responsible roles, and its deadline offsets defined in advance. Accounting-specific project management literature ranks reusable templates and recurring workflow automation among the highest-priority features a firm should look for. Templates do more than save setup time. They move best practice out of any one person's head and into the firm's system, so that when a senior staff member leaves, the knowledge of how the engagement is supposed to run doesn't leave with them.
This problem appears at scale in the case of a large U.S. assurance, tax, and advisory firm with more than 80 offices, which identified project management as a priority skill across the entire organization after its teams struggled to collaborate across business lines, use a shared PM vocabulary and toolset, or apply consistent best practices from office to office. That firm's problem was never technical tax knowledge. It was coordination at scale, a problem systematic intake, capacity visibility, and shared templates are built to solve.
One complication is moving faster than most firms are adjusting for it. AI is shifting what the actual work consists of: the profession is moving from manual data entry toward data validation, where staff review AI-processed output for accuracy rather than producing it from scratch. Firms that have adopted AI tools without updating how they assign tasks are still staffing according to an older version of the job, and that mismatch between tool and staffing model is its own kind of operational risk.
How billing model choice reinforces or undermines the production framework
None of the three changes above pay off fully if the firm's billing model works against them. Under an hourly model, the savings generated by better intake, better capacity planning, and reusable templates don't turn into competitive advantage. They turn into margin compression, because the firm is now doing the same work in less time for the same or lower fee.
Fixed-fee and value-based pricing flip that incentive. When efficiency gains accrue to the firm as margin rather than getting passed back to the client as a shorter bill, the production framework and the pricing model start working in the same direction instead of against each other.
That only works, though, if the scoping behind the fixed fee is rigorous. Without accurate upfront scoping, the same scope-creep problem described earlier comes back and attacks margin from the opposite side: the firm delivers more work than it priced for, and a flat fee gives it even less room to recover that gap than hourly billing would have. The sequencing matters here. Moving to fixed-fee pricing before the workflow and intake systems are in place is a high-risk move, because the firm would be locking in a price without the operational visibility to know whether that price is sustainable. The production system has to go in first. The pricing model that rewards efficiency only makes sense once the firm actually has an efficient, visible process to price against.
Where purpose-built tools fit into the framework
Software has a real role in all of this, but it plays a supporting role, not the leading one. A tool can enforce a workflow template, surface capacity data in real time, and flag a stalled intake before it becomes a missed deadline. None of that happens automatically just because a firm buys a subscription. The process has to exist first; the tool exists to make that process easier to run consistently across every engagement and every staff member, not to invent the process on the firm's behalf.
That has direct implications for what a firm should actually look for in a platform. Priority should go to tools built specifically around the features this piece has already laid out as load-bearing: reusable, deadline-aware templates for each recurring engagement type, real-time capacity visibility that lets a manager see available hours before assigning new work, and structured intake tracking that treats document collection as a monitored pipeline stage rather than an open-ended email thread. A tool that offers all three but gets adopted without retraining staff on the new process will end up only partially used, which is the same failure pattern seen across the broader survey data on stalled automation efforts.
The firms that get this right treat the software decision as the last step in a redesign. The production framework, the capacity discipline, and the pricing model all have to be worked out first. Once they are, the right tool simply makes that system easier to run at the scale tax season demands.